Economic uncertainty changes how people use money. Consumers may cut discretionary spending, delay purchases or rely more heavily on credit, while businesses must balance incoming revenue against payroll, supplier payments and other obligations. In these conditions, knowing where money stands today is useful, but anticipating where it will fall short tomorrow can be even more valuable.
Fintech can help close that gap. Digital financial tools can identify potential cash shortfalls, surface savings opportunities and provide timely guidance that helps people act before a difficult financial situation becomes a crisis. The challenge is making those tools useful in real life, rather than simply adding more dashboards and notifications.
Members of the Senior Executive FinTech Think Tank offer three perspectives on how predictive financial support, contextual savings and cash-flow forecasting can help businesses and consumers navigate uncertainty with greater control.
“Fintech will shift from merely facilitating transactions to providing predictive financial survival tools.”
Move From Tracking Money to Preventing Financial Stress
Financial technology has traditionally helped people complete transactions, monitor balances and access credit. But when economic conditions change quickly, these capabilities may not be enough. A consumer can see a declining account balance without knowing which expense to adjust first, and a small business can track invoices without recognizing an upcoming liquidity problem until it is too late.
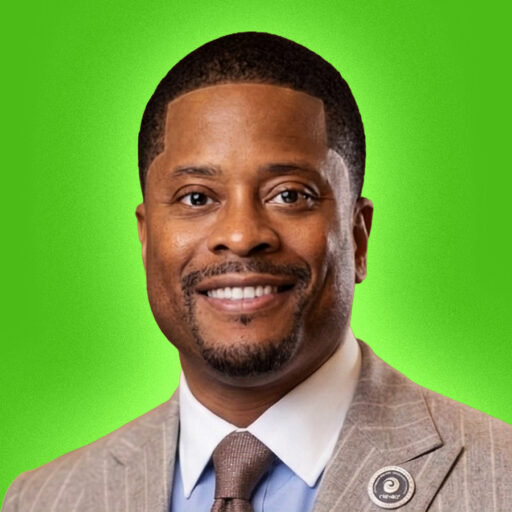
Reco McCambry, Founder, President and CEO of Novae, sees an opportunity to move fintech toward prevention. Novae provides access to credit, capital and entrepreneurship resources, including credit-management software and commercial lending. McCambry also founded FreeDebtHelp.com, which provides debt-relief services, giving him a perspective on the challenges people face when financial obligations become difficult to manage.
“Fintech will shift from merely facilitating transactions to providing predictive financial survival tools,” McCambry says.
That shift changes the purpose of financial technology. Instead of waiting for customers to notice their balances falling or their debt growing, tools could help them recognize warning signs earlier and consider practical options while they still have time to respond.
McCambry points to two capabilities that could make this possible: alternative data and flexible credit solutions. Used responsibly, alternative data can help fintech companies understand financial circumstances that conventional measures may not fully capture. Agile credit options can give eligible businesses and consumers additional flexibility when timing mismatches or unexpected expenses threaten their ability to meet obligations.
“By leveraging alternative data and agile credit solutions, fintechs can offer proactive debt management and tailored liquidity options before a crisis hits,” McCambry says.
The opportunity is significant because financial vulnerability can exist even when someone appears to be managing day-to-day expenses. The Federal Reserve’s 2025 report on the economic well-being of U.S. households, published in May 2026, found that average credit card balances had increased by more than 35% since 2023 among people who reported difficulty getting by. The findings illustrate why financial tools need to help people understand not only what they owe but also how their financial position is changing.
For fintech providers, the practical lesson is to turn financial information into timely choices. A warning about rising debt is more useful when there’s a clear explanation of the risk and possible next steps. A cash shortfall alert is more actionable when customers can review upcoming bills, assess available funds and explore appropriate alternatives.
McCambry summarizes the objective as giving people greater control over their financial decisions: “We must give users the executive capacity to navigate turbulence, not just track their declining balances as the storm approaches.”
That means designing technology around what users can do next, not simply what the system can detect.
“Fintech’s most important role is building financial resilience by delivering contextual help in real time.”
Put Financial Guidance Where Decisions Happen
Predictive tools can help users anticipate trouble, but financial support also needs to reach people at the moment they are making decisions. Consumers rarely manage their finances in a single place. They move between banking apps, online stores, subscription services, payment platforms and other digital environments. Each interaction can influence spending, yet financial guidance often remains separated from those decisions.
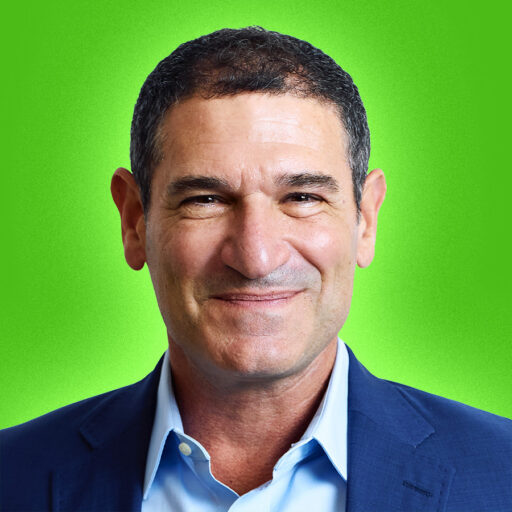
Jordan Glazier, Founder and CEO of Wildfire Systems, sees an opportunity to make financial assistance more immediate and relevant. Wildfire powers white-label shopping rewards and retail media programs for financial services and technology partners. Its platform connects users with cashback offers, digital coupons and other savings opportunities across more than 50,000 merchant programs in over 50 countries.
“Fintech’s most important role is building financial resilience by delivering contextual help in real time,” Glazier says.
A generic recommendation to spend less may be easy to ignore, especially when a consumer is already trying to stretch a limited budget. A relevant alert tied to a specific payment, recurring charge or shopping decision can give that person a clearer opportunity to act.
Glazier offers examples of how such support could work: “There are fintechs that can flag a payment that might cause an account to be overdrawn, identify a forgotten subscription or show savings and rewards as someone shops.”
These interventions address different points in the financial decision-making process. An overdraft warning can prompt a customer to review the timing of a payment. A forgotten-subscription alert can empower someone to reconsider an expense that no longer provides value. Savings and rewards can help shoppers compare options as they are deciding what to buy.
The goal is not to encourage more transactions by default. It is to make the financial implications of everyday decisions easier to see, helping consumers identify opportunities to preserve cash without requiring them to search for assistance separately.
The 2026 J.D. Power U.S. Financial Health Support and Advice Study found that 40% of bank customers were financially vulnerable, while fewer than one in six knew their bank offered financial health tools. The study also found that 53% of customers had turned to AI for financial advice in the preceding three months.
Those findings point to a mismatch between the support available and the support people recognize or use. Even when financial institutions invest in tools, customers may not know they exist or may not engage with them consistently.
Glazier sees fintech as a way to close that gap through existing digital touchpoints.
“The need exists,” Glazier says. “Consumers want help, but don’t always know where to find it.”
That creates an opportunity for banks, fintech providers and merchants to make useful guidance easier to discover. Banks can integrate financial health resources into everyday account activity, while commerce platforms can surface relevant savings information during shopping. The key is to ensure recommendations serve the user’s interests and clearly communicate why an offer or prompt matters.
Glazier advises fintech leaders to make guidance “proactive, personalized and built into where people are already banking, shopping and talking to AI.”
For businesses, this approach can also support customer engagement by making financial tools more useful in daily life. Success should extend beyond clicks or redemptions. Providers should examine whether customers save money, avoid preventable fees or develop more consistent financial habits.
“I see fintech’s role as helping consumers and businesses manage the gap between when money arrives and when bills fall due.”
Use Cash-Flow Forecasts to Act Before Bills Come Due
For consumers and businesses alike, financial pressure often emerges from a timing problem. Money may be coming in, but not soon enough to cover a bill. A customer may have a paycheck arriving in several days while a payment is due tomorrow. A business may have signed a new contract but still needs to cover payroll before the customer pays the invoice.
These situations show why monitoring balances alone can provide an incomplete picture. Financial resilience also depends on understanding when money will arrive, when obligations must be paid and how much flexibility remains between the two.
Faturoti Kayode, an Internet Entrepreneur and Co-founder of Breet, works in cryptocurrency and payment infrastructure. Breet enables individuals and businesses across Africa to make cryptocurrency spendable through its consumer app, business dashboard and developer API. The company reports serving more than 500,000 users and processing over $1 billion in transactions, giving Kayode a direct connection to the practical challenges of moving money across digital payment systems.
“I see fintech’s role as helping consumers and businesses manage the gap between when money arrives and when bills fall due,” Kayode says.
That gap can be difficult to manage when income is irregular, customer payments are delayed or spending patterns change unexpectedly. Cash-flow forecasting can help by bringing expected income and scheduled obligations into one view, allowing users to identify potential shortfalls before they become urgent.
Kayode recommends turning those forecasts into early prompts: “I’d turn cash-flow forecasts into early prompts to cut optional spending or request a different payment date, giving users time to adjust before they take on more debt.”
The distinction between an early prompt and a late warning is important. Once a payment is overdue, the available choices may be narrower and the consequences more expensive. Before the due date, a consumer might reduce discretionary spending, move a planned purchase or contact a provider to change a payment date. A business might follow up on an outstanding invoice, adjust inventory purchases or coordinate payment terms with a supplier.
These actions are not a substitute for sufficient income or sustainable financing. They can, however, give users more time to make informed choices rather than relying immediately on additional borrowing. For households already facing tight budgets, identifying a shortfall before rent or another essential bill is due may create a valuable window to respond.
For small businesses, the same principle applies at a different scale. Revenue on paper does not necessarily mean cash is available when payroll, suppliers or operating expenses must be paid. A forecasting tool that accounts for expected receipts and known obligations can help owners see when the timing of cash inflows may create pressure.
The usefulness of these systems depends on the quality of their inputs. Forecasts should distinguish confirmed income from uncertain payments, account for recurring and irregular expenses and make assumptions visible. If a system treats a delayed invoice as guaranteed revenue, its apparent precision can give users false confidence.
Fintech providers should therefore prioritize understandable forecasts and practical recommendations. Users need to know which bills are approaching, how confident the system is in expected income and what actions may help reduce the gap. Alerts should support decisions without overwhelming people with notifications or encouraging them to take on more unnecessary debt.
Kayode’s recommendation is ultimately about giving people time to respond. Forecasting becomes valuable when it changes what a user can do before a financial obligation becomes a problem.
Practical Steps to Build Financial Resilience
- Use predictive tools to identify financial trouble early. Help consumers and businesses anticipate debt risks and cash shortfalls before they become urgent problems.
- Deliver financial guidance where decisions happen. Integrate relevant alerts, subscription reviews and savings opportunities into the banking and shopping experiences people already use.
- Turn cash-flow forecasts into timely action. Help users anticipate gaps between incoming money and upcoming bills so they can adjust spending or payment dates before taking on more debt.
Building the Next Generation of Financial Tools
Fintech can play a meaningful role in helping consumers and businesses navigate economic uncertainty, but the opportunity extends beyond making payments faster or providing another way to access credit. Predictive debt management, contextual savings and cash-flow forecasting can help users recognize risks sooner and make decisions with more time and information. The most useful tools will turn financial data into clear, timely actions rather than leaving users to interpret a changing balance on their own.
The next stage of fintech will depend on how effectively providers translate those capabilities into better financial outcomes. That means designing tools around real needs, making recommendations understandable and ensuring that flexibility does not become an invitation to take on unsustainable debt. As financial pressures and spending habits continue to evolve, fintech companies that help people anticipate problems, preserve cash and act confidently can become more valuable partners in financial resilience.
MOST POPULAR
AI Is Commoditized—Here's What Sets Great Brands Apart
9 Ways to Measure the Success of Your DEI Strategy
Inspiring Ideas. Actionable Insights.
Senior Executive's Email Newsletters Deliver Fresh Solutions to Today's Leadership Challenges.
Subscribe Free
How AI Is Rewriting the Timeline for Useful Robots
Do You Have What It Takes to be a CEO?
Fintech Banking: How to Protect Your Business and Cash