Artificial intelligence is changing how financial services companies analyze data, serve customers and move money. From conversational banking tools to automated payment systems and AI-assisted financial management, the technology offers opportunities to improve speed, efficiency and access. But when a decision affects someone’s financial security, a fast answer is not necessarily a reliable one.
The challenge is determining where AI adds value and where its limitations require human judgment. Members of the Senior Executive FinTech Think Tank bring perspectives from payments infrastructure, AI product development, cryptocurrency and consumer finance. Their insights point to four areas where financial services leaders should proceed thoughtfully: interpreting incomplete information, earning customer trust, building commercial relationships and responding to people facing financial hardship.
“I still don’t trust generative AI to recognize when it lacks enough context for a financial decision.”
Recognize When the Data Doesn’t Tell the Whole Story
AI can identify patterns, summarize records and generate recommendations, but those capabilities don’t guarantee that a system understands when its information is insufficient. In financial services, that distinction matters because customer records can be incomplete, contradictory or missing details that would change the appropriate response.
Faturoti Kayode, an Internet Entrepreneur and Co-founder of Breet, understands the operational demands of digital financial services. Breet is a cryptocurrency and payment infrastructure platform that makes crypto spendable for individuals and businesses across Africa. Its reported scale, with more than 500,000 users and over $1 billion in processed transactions, gives Kayode a practical perspective on the importance of reliable digital financial experiences.
Kayode identifies a fundamental weakness in generative AI: knowing when it lacks the context needed to make a sound decision.
“I still don’t trust generative AI to recognize when it lacks enough context for a financial decision,” he says. The concern is not only whether AI can analyze available information. It’s whether the system can recognize that the information may not justify its answer.
Kayode recommends testing AI against incomplete or contradictory customer records and establishing a separate process to route uncertain cases to a person. He explains why that distinction matters: “a confident explanation can hide the need to ask another question.”
That warning aligns with the National Institute of Standards and Technology’s Generative AI Profile, which identifies confabulation, commonly called hallucination, as a risk when generative AI presents false or inaccurate information confidently. Such errors are particularly consequential when people rely on generated outputs to make important decisions.
The broader industry is confronting similar challenges. The Cambridge Centre for Alternative Finance’s 2026 Global AI in Financial Services Report identifies data quality and completeness as leading barriers to wider AI adoption. It also highlights unreliable outputs, privacy and insufficient human oversight among the risks facing financial institutions.
For financial services leaders, the practical implication is straightforward: A model should not be expected to compensate automatically for missing or conflicting information.
The goal is not to eliminate automation. It is to ensure automation recognizes its limits before a customer experiences the consequences.
“AI can’t make a sale!”
Understand Why Automation Cannot Replace a Sales Relationship
AI can help financial services companies process information, streamline customer interactions and support payment operations. Yet completing a transaction is not the same as persuading a customer to trust a business, understand its offering or choose it over a competitor.
Allen Kopelman, CEO of Nationwide Payment Systems Inc., brings a payments and business-to-business perspective to this distinction. His company helps businesses across retail, hospitality, wholesale, e-commerce and other sectors improve cash flow through payment technology and relationship-based support. Kopelman also hosts the B2B Vault podcast, which explores sales, AI, operations and business growth.
His response begins with a direct observation: “AI can’t make a sale!”
The point is relevant to the financial services industry in which customer acquisition and retention depend on more than the mechanics of moving money. Merchants may compare payment providers based on pricing, settlement speed, fraud prevention and accounting integration. But they may also need help understanding the trade-offs, resolving operational problems and deciding whether a provider is a dependable long-term partner.
AI can support these interactions by organizing product information, answering routine questions and helping employees prepare for conversations. It can also make recommendations based on customer data. However, those functions do not automatically establish the credibility or mutual understanding needed to win a business relationship.
Kopelman emphasizes the practical value in financial technology. He says cryptocurrency and stablecoins create opportunities through “faster cross-border payments, lower transaction costs, improved settlement times and giving businesses more payment options.” He also stresses that digital money movement must be secure and commercially useful, rather than driven by speculation.
That perspective offers a useful distinction for AI adoption, too. A technology’s novelty is not the same as its business value. Financial services providers must connect automation to outcomes customers actually care about, including fewer payment delays, simpler operations and dependable support.
The same principle applies when AI is used in customer-facing sales. An automated assistant might explain a fee or outline a product’s features, but a complex prospect may need a conversation that accounts for specific business constraints, competing priorities or concerns that emerge only through a human-to-human discussion.
Kopelman’s viewpoint is a reminder that digital financial innovation should complement reliable payment infrastructure and human support rather than treating technology as a substitute for either.
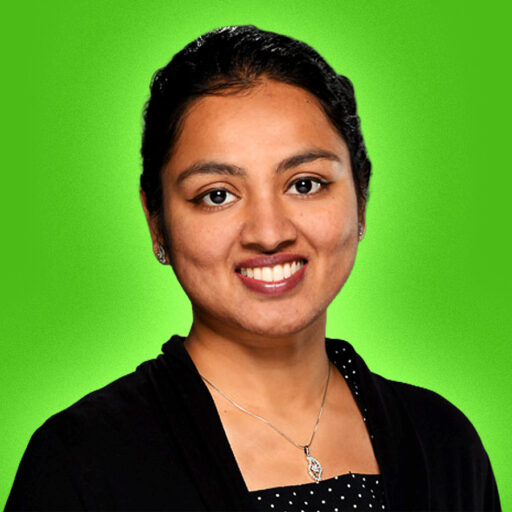
“The leaders driving AI innovation have failed to gain the trust of users and society as a whole.”
Build Trust Before Expanding AI’s Role
Even when AI performs a task accurately, customers may hesitate to rely on it with sensitive financial information. Banking and financial management involve questions of privacy, accountability and control, making trust a central consideration in the technology’s adoption.
Banu Raghuraman, AI Lead Product Manager at Perficient, brings more than 15 years of experience building customer experiences and software solutions, primarily in fintech, payments and healthcare. Her work includes product development involving mobile banking, real-time payments and conversational intelligence.
“Rather than AI technology itself, I believe the leaders driving AI innovation have failed to gain the trust of users and society as a whole,” Raghuraman says.
Her concern includes the ethical and legal questions that arise as AI systems become more sophisticated. She points to the risks of organizations governing AI themselves and developing systems capable of building other AI systems. In her opinion, “there is not enough emphasis placed on ethics, legalities, cost to human values and lives (in some cases).”
For financial services companies, those concerns have practical implications. Customers need to understand how their information is used, what role AI plays in a recommendation and who is accountable when something goes wrong. A system may be technically capable of answering a banking question, but that alone does not establish that the customer should trust its answer or authorize it to take action.
Raghuraman acknowledges that AI already plays a role in financial management advice, but cautions that it will take time for society to become comfortable with AI handling more banking activities. That distinction matters: Using AI to explain spending patterns is different from giving it authority to move funds, make consequential decisions or act without meaningful oversight.
The U.S. Government Accountability Office’s 2025 review of AI use and oversight in financial services outlines the potential benefits of AI but also the risks: lending bias and cybersecurity threats. Its findings reinforce the need for financial institutions to evaluate not only what AI can do but also the risks associated with its use.
Trust is not created through a disclaimer or a product launch. It requires clear accountability, understandable communication and safeguards that work in practice.
Financial institutions that treat trust as part of product design can make AI more useful without asking customers to accept unnecessary uncertainty.
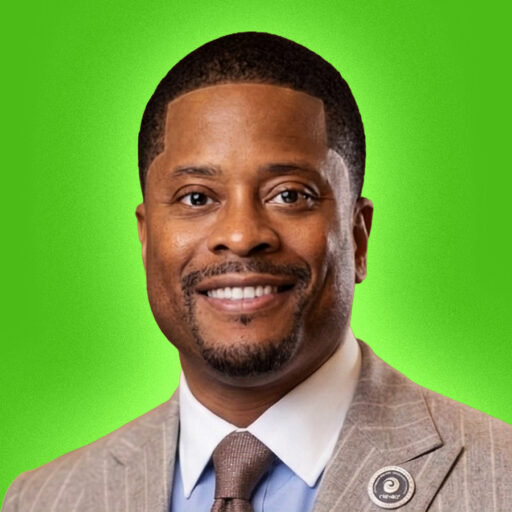
“Algorithms fail to understand the nuanced human reality behind a missed payment or a sudden market pivot.”
Respond to Financial Hardship With Context and Empathy
Financial services decisions often involve circumstances that are difficult to capture in a spreadsheet. A missed payment, a sudden drop in income or a business facing an unexpected expense may appear as a risk signal in a model. But the underlying circumstances can vary substantially, and a pattern alone does not explain what a customer is experiencing or what kind of assistance may be appropriate.
Reco McCambry, Founder, President and CEO of Novae, focuses on expanding access to credit, capital and entrepreneurship for consumers and small businesses. Novae provides financial services and tools that include consumer financing, commercial lending access and credit management software. McCambry also founded FreeDebtHelp.com, which provides debt relief services, giving him experience in consumer financial challenges and access to financial resources.
McCambry identifies a specific limitation: “AI still cannot replicate executive empathy and context-driven judgment during a financial crisis.”
He recognizes that algorithms are effective at analyzing risk and identifying spending patterns. However, he draws a line between detecting a financial problem and understanding the circumstances behind it. As he explains, algorithms “fail to understand the nuanced human reality behind a missed payment or a sudden market pivot.”
That distinction is particularly important in lending, debt management and other services where a decision can affect a person’s financial options. A missed payment may reflect a temporary disruption, an ongoing affordability problem or a more complicated set of circumstances. Automated systems can identify the event, but financial institutions should be careful about treating the signal as a complete explanation.
Human judgment does not mean ignoring risk, waiving standards or making decisions without evidence. Instead, it means allowing appropriate context to inform how a case is reviewed and whether additional information is needed. Employees can ask follow-up questions, explain available options and assess circumstances that may not be represented in structured data.
McCambry connects that human element directly to trust, saying that “True leadership in financial services requires a human element to build trust when customers are facing extreme adversity.”
His perspective highlights a broader challenge for AI adoption. Efficiency is valuable, but financial services providers must also consider whether their systems help people understand decisions and navigate difficult moments. A process that reduces handling time but leaves customers unable to explain their circumstances may undermine the relationship it is intended to improve.
The objective is to combine AI’s ability to identify patterns with the human capacity to understand circumstances. In high-stakes financial interactions, that combination can support more informed decisions without assuming that every customer situation can be reduced to a model’s output.
Practical Ways to Keep Human Judgment in the AI Loop
- Test AI with incomplete and contradictory information. Establish escalation rules that prevent uncertain outputs from becoming consequential financial decisions without additional review.
- Use AI to support sales, not replace customer relationships. Automate research and routine follow-ups while preserving human involvement in complex negotiations and trust-building conversations.
- Make transparency and accountability part of AI design. Explain how AI influences customer interactions, test for risks and provide clear routes to human assistance.
- Build hardship-sensitive review processes. Ensure customers can explain unusual circumstances and have appropriate cases evaluated by employees who can apply context and empathy.
Make Human Judgment a Competitive Advantage
AI can help financial services companies process information faster, recognize patterns and deliver more responsive experiences. But the insights from the FinTech Think Tank members point to limits that matter when systems encounter uncertainty, must earn customer confidence or influence decisions with significant financial consequences. The challenge is not whether to adopt AI, but how to define its role and ensure its outputs remain useful, reliable and accountable.
As financial institutions expand AI adoption, the strongest strategies will pair automation with clear escalation paths, meaningful oversight and customer-centered design. By testing systems against real-world complexity and keeping people involved where context matters most, fintech companies and traditional financial institutions can capture AI’s benefits without mistaking a confident answer for sound judgment.
MOST POPULAR
9 Great New Ideas for a Better Annual Company Meeting
9 Ways to Measure the Success of Your DEI Strategy
Inspiring Ideas. Actionable Insights.
Senior Executive's Email Newsletters Deliver Fresh Solutions to Today's Leadership Challenges.
Subscribe Free
Is AI Dangerous? How to Interpret Warnings From Experts
AI Is Commoditized—Here's What Sets Great Brands Apart
Co-Creation, Not Control: Building Brand Communities Fans Love